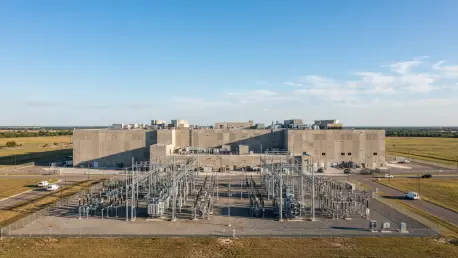
The rapid integration of sophisticated machine learning models into every facet of the global economy has transformed the data center from a silent storage utility into the most contentious piece of physical infrastructure in the modern era. These facilities currently serve as the essential backbone of the digital world, facilitating everything from instantaneous financial transactions to the vast computational demands of generative artificial intelligence. Currently, the industry is experiencing a surge in capital investment as technology giants and institutional funds race to secure capacity. This expansion, however, has placed data centers under an intense regulatory microscope, as municipal governments and local communities struggle to balance the clear economic benefits against the massive consumption of electricity and water.
The current industrial segment is no longer a niche infrastructure play but a critical national asset that attracts intense public scrutiny. As the physical manifestation of the internet, data centers have transitioned into high-stakes developments that can define the economic trajectory of an entire region. Despite their importance, the sheer scale of modern projects has led to a cooling of the once-warm welcome they received from local authorities. Developers now find themselves navigating a terrain where every kilowatt of power and every gallon of cooling water is a point of contention, forcing a shift from simple construction to complex community and environmental diplomacy.
The State of the Global Data Center Industry
The data center industry is currently operating at a fever pitch, driven by a global economy that has essentially moved entirely to the cloud. Massive capital expenditures are the norm as companies scramble to build out the high-density configurations required for modern workloads. This growth is not merely about more servers; it is about the transition to specialized compute environments that can handle the heavy lifting of real-time data processing and global logistics. The result is a sector that is more vital than ever but also more resource-intensive, pushing the limits of existing power grids and water supplies.
This industrial evolution has transformed data centers from passive warehouses into active, power-hungry hubs that are increasingly viewed as competitors for local resources. While they bring significant tax revenue and high-value jobs, the physical footprint and utility requirements of these facilities have sparked a new wave of skepticism among policymakers. As governments weigh the digital sovereignty provided by local data infrastructure against the environmental strain, the industry is seeing a transition from a deregulated expansion phase to one defined by strict oversight and strategic resource management.
Evolving Market Trends and Growth Projections
Emerging Technologies and Shifting Consumer Behaviors
The primary catalyst for recent industry shifts is the explosive demand for generative artificial intelligence, which requires a radical redesign of traditional facility layouts. Consumer behavior has also pivoted, with an increasing reliance on real-time processing and low-latency services that demand data be stored closer to the end user. This trend is driving the rise of “edge” data centers in dense urban hubs where land is at a premium and zoning laws are historically restrictive. Simultaneously, sustainability has become a non-negotiable requirement, as corporate players seek green solutions to meet aggressive environmental goals in a market that is increasingly sensitive to carbon footprints.
Market Data and Forward Looking Performance Indicators
Despite the proliferation of local resistance, global data center capacity is projected to grow significantly from 2026 to 2030. Performance indicators show a steady increase in absorption rates across major markets, even as land scarcity forces developers to look toward secondary regions for expansion. Forecasts suggest that while the physical number of new facility starts might be tempered by localized ballot initiatives, the total value and compute density of each project will rise. The industry is effectively entering a phase where quality and efficiency supersede raw quantity, and success is defined by a developer’s ability to navigate complex regulatory environments.
Overcoming Regulatory and Resource Challenges
The data center industry is facing a growing wave of localized pushback that often manifests as construction bans, temporary moratoriums, or sudden zoning reclassifications. These challenges are fueled by public anxiety over noise pollution, the aesthetic impact on rural landscapes, and the perceived drain on local utilities. To overcome these hurdles, developers are adopting a more proactive stance toward community engagement, moving away from closed-door planning toward transparent, “good neighbor” policies. This includes investing in shared infrastructure that benefits the broader community, such as upgraded power substations or improved water treatment facilities that serve more than just the data center itself.
Strategic solutions also involve the creative use of brownfield sites, transforming decommissioned industrial properties into high-tech hubs to minimize the environmental footprint. Legal strategies are becoming more aggressive as well, with firms using litigation to challenge the validity of retroactive regulatory shifts that threaten already-vested projects. By demonstrating that data centers are a net positive for local resilience—often providing the capital needed for long-delayed utility upgrades—developers can turn potential opponents into partners. The focus has moved toward a model of coexistence, where the digital economy supports rather than supplants local community interests.
Navigating the Complex Legal and Regulatory Landscape
The legal environment for digital infrastructure is shifting from a hands-off approach to one defined by stringent compliance and standardized oversight. Significant new laws now target specific metrics such as Power Usage Effectiveness and water conservation, requiring facilities to meet high efficiency targets to maintain their permits. Moreover, data centers are increasingly classified as critical infrastructure, bringing them under the purview of national security regulations that govern physical and cybersecurity. Compliance is no longer just a matter of following local building codes; it involves navigating a hierarchy where federal mandates often clash with local home-rule ordinances.
Developers must now conduct exhaustive legal audits to ensure their projects remain viable under these evolving standards. The risk of sudden regulatory changes has made the securing of vested rights a top priority in the early stages of development. Legal teams are focusing on constitutional protections, such as the Dormant Commerce Clause, to prevent local governments from unfairly targeting data centers in ways that disrupt interstate commerce. As the legal landscape becomes more crowded, the ability to interpret and anticipate regulatory shifts is becoming as important as the engineering that goes into the servers themselves.
Future Directions in Digital Infrastructure Law
Potential Market Disruptors and Innovation Trends
Looking ahead, the industry will likely see a clash between traditional local land-use authority and federal preemption as data centers become even more vital to the national interest. Emerging technologies like modular data centers and hydrogen fuel cells could disrupt current zoning categories, requiring entirely new legal definitions for digital infrastructure. If facilities can operate independently of the municipal grid, many of the current resource-based arguments for bans will lose their legal standing. We may also see a move toward federalizing certain siting decisions to ensure that local resistance does not sabotage national connectivity or digital sovereignty.
Global Economic Conditions and Growth Areas
The future of data center development will be heavily influenced by the cost of capital and the availability of specialized labor in a competitive global market. Future growth areas are expected to emerge in jurisdictions that offer high levels of regulatory certainty, providing clear frameworks rather than volatile, ballot-driven restrictions. International competition for digital leadership will continue to drive domestic policy, as national governments seek to protect their data assets and attract high-tech investment. The industry remains strong for those who can integrate legal resilience into their pipelines, balancing the needs of the local community with the protections offered by the constitutional framework.
Summary of Findings and Strategic Recommendations
The analysis of the regulatory climate during this period demonstrated that a multi-faceted legal approach was essential for protecting infrastructure investments. Developers learned that securing vested rights early in the permitting process provided the strongest defense against the wave of restrictive ballot initiatives that swept through many jurisdictions. Legal experts successfully leveraged the Dormant Commerce Clause to challenge local bans that imposed excessive burdens on the national digital economy. Furthermore, the industry found that proactive utility investments helped mitigate the political risks of high resource consumption.
Strategic consultants recognized that the most resilient developers were those who established legal standing through early permitting and community partnership agreements. They pivoted toward brownfield developments that bypassed the most aggressive zoning restrictions and utilized innovative cooling technologies to meet new environmental standards. It was ultimately the integration of federal statutory protections with local environmental mitigation that preserved the viability of the digital backbone. Moving forward, stakeholders prioritized regulatory certainty over rapid expansion, ensuring that every project was backed by a robust legal defense and a clear commitment to local resource stability.